What Cryptocurrency Is and How It Differs from Traditional Money
Think of the money in your bank account. It exists because a bank says it does, and that bank answers to a central authority – usually a government or central bank. Cryptocurrency works differently. It's a form of digital money that runs on a network of computers spread across the world, with no single institution in charge.
What Makes It Different from Regular Money
Traditional money exists in physical form and as digital records held by banks. Cryptocurrency exists only as digital entries on a shared public record called a ledger. Anyone can view that ledger, and no single person or organization controls it. When you send cryptocurrency to someone, that transaction gets recorded publicly – not by a bank, but by the network itself.
A Brief History of How It Started
In October 2008, a person or group using the name Satoshi Nakamoto published a whitepaper describing a peer-to-peer electronic cash system called Bitcoin. The first block of the Bitcoin blockchain – known as the genesis block – was mined in January 2009. By May 2010, a programmer named Laszlo Hanyecz made what is widely considered the first real-world commercial transaction using Bitcoin, paying 10,000 BTC for two pizzas.
Other blockchains followed. Ethereum launched in 2015, introducing the ability to run programmable agreements on a blockchain. Hundreds of other networks have since emerged, each with different rules and purposes. The technology moved from a niche experiment to a global infrastructure used by millions.
How Blockchain Keeps a Shared Record
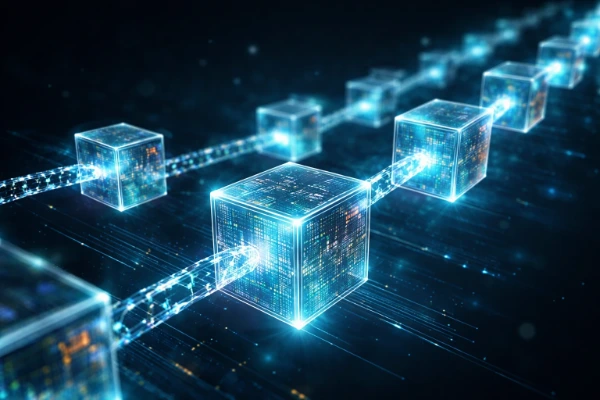
A blockchain works by organizing information into a sequence of connected records rather than storing everything in one central database. To understand why this system is difficult to alter, it helps to look at the individual pieces that make up the chain.
What a Block Actually Contains
Each block is a small bundle of data. It holds a group of recent transactions, a timestamp showing when it was created, and a short string of characters called a hash. Think of a hash as a digital fingerprint – unique to that block's contents. Change even one character inside the block, and the hash changes completely.
How Blocks Link Together
Every new block also stores the hash of the block before it. That connection is what creates the chain. Block 500 carries the fingerprint of block 499, which carries the fingerprint of block 498, and so on back to the very first block. Alter an old block, and its hash changes, which breaks the link to every block that follows. Fixing that would mean recalculating thousands of blocks in sequence.
Linking blocks is only part of the system. Blockchain networks also rely on many separate computers keeping their own copies of the same record, which reduces dependence on a single database or administrator.
Why Copies Matter
The ledger isn't stored in one place. Thousands of computers around the world each hold an identical copy. Imagine a thousand people all holding the same notebook. If someone quietly edits page 12 of their copy, everyone else's notebooks still show the original. The network simply rejects the version that doesn't match the majority.
Having many copies of the ledger also makes older information increasingly difficult to rewrite. A successful change would have to overcome both the structure of the chain and the network participants maintaining consistent records.
Why Old Records Are So Hard to Change
Rewriting history on a blockchain means outpacing thousands of computers simultaneously, all cross-checking each other in real time. The further back a transaction sits, the more blocks have been stacked on top of it, and the harder it becomes to tamper with. That accumulation of blocks is what gives the record its reliability.
How Bitcoin Transactions Move Through the Network
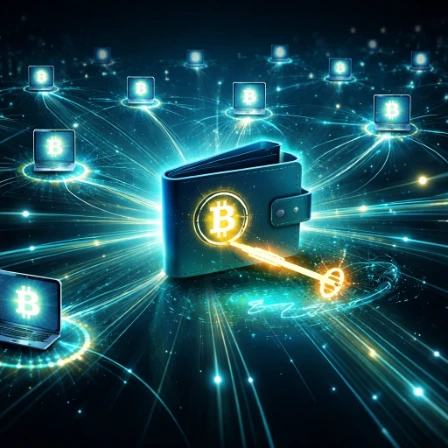
Every transaction starts with the sender. When you want to send Bitcoin to someone, your wallet uses your private key to create a digital signature. Think of it like a wax seal on a letter. It proves the instruction came from you without revealing the key itself.
Once signed, the transaction is broadcast to the Bitcoin network. Thousands of computers, called nodes, receive a copy of it almost instantly. Each node checks the basics: does the sender actually have enough Bitcoin? Is the signature valid? Transactions that fail these checks get dropped.
Valid transactions sit in a waiting area called the mempool. Miners pick them up and group them into a block. Before that block can be added to the chain, the miner has to solve a computational puzzle. This takes real processing power and time. When one miner solves it, they broadcast the new block to the network. Other nodes verify the solution and, if it checks out, add the block to their copy of the chain. The transaction is now confirmed.
Each new block points back to the one before it, which is why rewriting history would mean redoing the work on every block that followed. That's what makes the record so resistant to tampering.
One design feature worth understanding is the 21 million coin limit. Satoshi Nakamoto built a hard cap into the protocol. No more than 21 million Bitcoin can ever exist. It's a fixed rule in the code, not a policy decision anyone can reverse later.
Mining, Staking, Wallets, and the Terms Beginners Need
Behind every transaction sits a set of systems and tools that keep cryptocurrency networks running honestly. Three of the most important are the two methods for creating new blocks, the wallets people use to access their funds, and the shared vocabulary that ties it all together.
How New Blocks Are Created: Mining and Staking
Proof of work is the older approach. Miners run specialized computers that race to solve a complex mathematical puzzle. The first to find the correct answer earns the right to add the next block and receives a small reward in cryptocurrency. The process demands significant electricity, which is one reason it attracts debate.
Proof of stake works differently. Instead of competing with computing power, validators lock up a portion of their own coins as collateral. The network selects a validator to add the next block, often weighted by how much is staked. If a validator tries to cheat, they risk losing their staked coins. Both methods serve the same purpose: reaching agreement across a network with no central referee.
Using cryptocurrency also requires a way to manage the keys connected to blockchain addresses. That is the role of a crypto wallet, although the term can be misleading because the coins themselves are not physically stored inside it.
What Is a Crypto Wallet?
Wallets don't actually hold coins. They store the cryptographic keys that prove ownership on the blockchain. A public key works like an address you share with others to receive funds. A private key is the password that authorizes spending. Anyone who has your private key has full control of your funds.
Hot wallets stay connected to the internet, making them convenient but more exposed. Cold wallets are offline devices, closer to a physical safe.
Glossary of Common Terms
Block – a batch of verified transactions added to the chain.
Hash – a fixed-length code that represents data; changing any input changes the hash entirely.
Node – a computer that holds a copy of the blockchain and helps validate transactions.
Private key – a secret code that authorizes transactions from your wallet.
Public key – a shareable address others use to send you cryptocurrency.
Token – a digital asset built on an existing blockchain rather than its own.
Gas fee – a small charge paid to validators for processing a transaction, common on Ethereum.
Decentralization – distributing control across many participants rather than one authority.
The Technology Is Easier Once the Basics Connect
Piece by piece, a clearer picture starts to form. Cryptocurrency is digital money that runs on decentralized networks, meaning no single bank or government controls it. The blockchain underneath it is a shared ledger, where transactions are grouped into blocks, each one linked to the last through a cryptographic fingerprint, and copied across thousands of computers worldwide. Bitcoin is one working example of this system, where every transaction is signed, broadcast, verified, and permanently recorded. New blocks get added through either mining, which uses computing power to solve mathematical puzzles, or staking, which requires validators to lock up coins as a form of commitment. Wallets don't hold coins directly. They store the private and public keys that prove ownership and authorize movement of funds. None of these ideas require a technical background to grasp. They just need a moment to connect.